Summary
Scope 3 emissions are the indirect greenhouse gas emissions in a company's value chain, from the goods it buys to the use and disposal of what it sells. The GHG Protocol splits them into 15 categories. For most large companies they are most of the footprint, so accurate measurement underpins credible targets, disclosure and reduction plans.
Last updated: 23 October 2026
What are Scope 1, 2 and 3 emissions?
Scope 1 is what you burn, Scope 2 is the energy you buy, and Scope 3 is everything else in your value chain. The GHG Protocol Corporate Standard, first published in 2001, set out this split. It is now the basis for most mandatory climate disclosure rules, including IFRS S2.
| Scope | What it covers | Example |
| Scope 1 | Direct emissions from sources the company owns or controls | Fuel burned in company boilers, furnaces and vehicles |
| Scope 2 | Indirect emissions from purchased electricity, steam, heating and cooling | Emissions at the power plant that supplies your factory |
| Scope 3 | All other indirect emissions across the value chain, upstream and downstream | Growing purchased raw materials, third-party freight, employee commuting, customers using and disposing of your products |
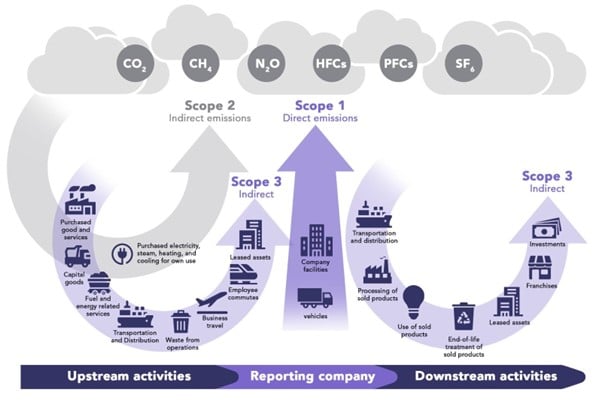
Source: adapted from the GHG Protocol.
For a deeper look at how each scope is counted, see our guide to GHG scope categories.
What are the 15 categories of Scope 3 emissions?
The GHG Protocol Corporate Value Chain (Scope 3) Standard (2011) defines 15 categories: eight upstream and seven downstream. Not every category applies to every company. The standard asks you to screen them all and explain any you leave out.
| # | Category | Upstream or downstream | What it includes |
| 1 | Purchased goods and services | Upstream | Producing the goods and services you buy |
| 2 | Capital goods | Upstream | Producing equipment, buildings and machinery you buy |
| 3 | Fuel- and energy-related activities | Upstream | Extracting, producing and transporting fuels and energy you use, not already in Scope 1 or 2 |
| 4 | Upstream transportation and distribution | Upstream | Moving purchased goods in vehicles you don't own |
| 5 | Waste generated in operations | Upstream | Third-party disposal and treatment of your waste |
| 6 | Business travel | Upstream | Employee travel in vehicles you don't own |
| 7 | Employee commuting | Upstream | Employees travelling to and from work |
| 8 | Upstream leased assets | Upstream | Operating assets you lease, if not in Scope 1 or 2 |
| 9 | Downstream transportation and distribution | Downstream | Moving sold products in vehicles you don't own |
| 10 | Processing of sold products | Downstream | Further processing of your intermediate products by others |
| 11 | Use of sold products | Downstream | Customers using your products |
| 12 | End-of-life treatment of sold products | Downstream | Disposal and treatment of your products after use |
| 13 | Downstream leased assets | Downstream | Operating assets you own and lease to others |
| 14 | Franchises | Downstream | Operating your franchises |
| 15 | Investments | Downstream | Emissions linked to your investments and lending |
The GHG Protocol is revising the Scope 3 Standard. Its Phase 1 progress update (31 March 2026) sets out proposed changes, and a full draft for public consultation is still to come. The 15 categories above remain the current rules.
How big are Scope 3 emissions compared with Scope 1 and 2?
For most companies Scope 3 is far larger than Scope 1 and 2 combined. In companies' 2023 disclosures, supply chain emissions alone averaged 26 times operational emissions, according to the CDP and BCG report Scope 3 Upstream: Big Challenges, Simple Remedies (June 2024). In retail the ratio was 92 times.
The share varies by sector. Companies that buy farm commodities, packaging or finished goods tend to have the highest Scope 3 share. Companies that run energy-intensive plants of their own tend to have a higher Scope 1 share.
Why should companies measure Scope 3 emissions accurately?
Because you can't reduce, report or set targets on what you can't see. Accurate Scope 3 data tells you where the emissions are, which suppliers and products matter most, and whether your actions are working. Rough estimates hide those answers.
Yet few companies get there. In the 2024 BCG and CO2 AI survey of nearly 2,000 companies, only 9% said they comprehensively report Scope 1, 2 and 3 emissions. We explain the main reasons in why Scope 3 is hard to measure.
Disclosure rules increasingly ask for Scope 3
More jurisdictions now require Scope 3, usually with a delay after Scope 1 and 2. The table below is a summary. Check our country posts and the sustainability reporting rules explainer for details.
| Rule | Scope 3 requirement (as of October 2026) |
| ISSB IFRS S2 (global baseline) | Required, with relief from Scope 3 in the first year of reporting |
| Australia AASB S2 | Required from an entity's second reporting year |
| California SB 253 | Scope 1 and 2 first due 10 November 2026; Scope 3 reporting starts in 2027 (California Air Resources Board, June 2026) |
| EU CSRD (ESRS E1) | Scope 3 reported where material; after the Omnibus I directive (in force 18 March 2026), scope narrows to companies with over 1,000 employees and over €450 million turnover from financial years starting 1 January 2027 |
| Singapore (SGX, ACRA) | Scope 3 mandatory from FY2026 for Straits Times Index constituents; voluntary for other listed companies (ACRA, 25 August 2025) |
| US SEC climate rule | Final rule (March 2024) dropped Scope 3; the SEC stopped defending the rule in 2025 |
Targets depend on it
Science-based targets need a Scope 3 baseline. If Scope 3 is a large share of your footprint, the Science Based Targets initiative (SBTi) expects a Scope 3 target. The SBTi is revising its net-zero standard; see what's changed in SBTi v2.
Customers and lenders ask for it
Your Scope 3 is your customers' Scope 1, 2 or 3. Large buyers with their own targets now send supplier questionnaires and set data requirements in contracts. Lenders and investors use the same figures for transition risk.
It shows where the cost and risk sit
Scope 3 data highlights carbon-intensive inputs, suppliers and routes. That is where carbon prices, supply shocks and customer demands will hit first. We cover this in more detail in the business case for reducing Scope 3.
How do you start measuring Scope 3?
Start with a screening of all 15 categories, then improve the data for the few that matter most. In practice that means:
- Map the value chain. List upstream and downstream activities for each category. See prerequisites for supplier engagement.
- Screen with spend data. A spend-based estimate shows which categories and suppliers are largest.
- Refine the hotspots. Move to activity data and supplier-specific data where emissions are highest. Our guide to Scope 3 calculation methods compares the options.
- Engage suppliers. Ask your biggest suppliers for primary data and work with them on reductions. See Scope 3 supplier engagement.
- Document and disclose. Record methods, emission factors and assumptions so auditors and stakeholders can follow your numbers. See data transparency in Scope 3 reporting.
What does this look like in practice?
Princes, the international food and drink group, used Terrascope to map its value chain and found that its top five activities made up more than 60% of its emissions. That told the team where supplier engagement would have the most effect. Read the Princes case study.
How Terrascope helps with Scope 3
Terrascope is built for companies whose footprint is mostly Scope 3, especially those that buy farm, food and packaging inputs. The platform:
- Screens all 15 categories from spend and activity data, then flags the hotspots worth refining.
- Matches each line of data to an emission factor and shows the data quality behind each result.
- Collects primary data from suppliers through Scope 3 supplier engagement tools.
- Brings ERP, procurement and supplier data into one place with Terrascope data management.
- Keeps an audit trail from source data to reported figure.
Not sure where your Scope 3 sits? Our value chain mapping workshop is free and helps you find your largest categories.
Frequently asked questions
Is Scope 3 double counting?
Within one company's inventory, no. Each tonne sits in only one scope. Across companies, yes by design: one company's Scope 1 is another's Scope 3. That overlap is intended. It gives every company in a value chain a reason to cut the same emissions.
What percentage of emissions are Scope 3?
It depends on the sector. In 2023 disclosures, supply chain emissions averaged 26 times operational emissions, and 92 times in retail (CDP and BCG, 2024). For most consumer goods, food and retail companies, Scope 3 is the large majority of the footprint.
Why is Scope 3 so hard to measure?
The emissions happen at suppliers and customers, not in your own operations. You depend on their data, which is often missing, estimated or in different formats. Most companies start with industry-average or spend-based factors and replace them with supplier data over time.
Is Scope 3 mandatory to report?
In a growing number of places. IFRS S2, Australia's AASB S2 and California's SB 253 require it after a transition period. Under the EU CSRD it is reported where material. Singapore requires it for STI constituents from FY2026. The US SEC rule does not require it.
Is Scope 3 included in net zero?
Yes. A credible net-zero target covers all three scopes. The SBTi expects companies to set Scope 3 targets when Scope 3 is a significant share of their emissions. Its net-zero standard is being revised, so check the latest version before setting targets.
Can you offset Scope 3 emissions?
Carbon credits don't reduce your Scope 3 inventory. Under the GHG Protocol and SBTi, credits are reported separately from your emissions. They can support action beyond your value chain, but targets have to be met by real reductions with suppliers, products and logistics.
Talk to a Scope 3 specialist
If you need a defensible Scope 3 baseline for a target or a disclosure deadline, speak to our team.