Summary
-
Your first reporting year opens before your first report is due. Group 2 companies report for financial years commencing on or after 1 July 2026, Group 3 from 1 July 2027. Scope 1 and 2 emissions in that first year are reviewed by an assurance provider, so the data has to be captured from day one of the year.
-
Your largest customers will ask for your emissions before ASIC does. Every company in scope must disclose Scope 3 from its second reporting year, and it gets those numbers from suppliers. Group 3 companies sit in those supply chains.
-
Assurance starts with the first report and tightens every year. Limited assurance over governance, strategy and Scope 1 and 2 in year one, over the whole report in years two and three, reasonable assurance over everything from year four.
If you run a Group 2 or Group 3 company, the date on your calendar is probably the one your first sustainability report is lodged with ASIC: 2027 for Group 2, 2028 for Group 3. The date that decides whether that report passes review is earlier. It is the first day of your first reporting year, when your Scope 1 and 2 measurement has to be running, your governance in place and your evidence trail started.
Who is in Group 2 and Group 3
A company falls into a group when it already prepares a financial report under Chapter 2M of the Corporations Act 2001 and meets at least two of three size tests at the end of the financial year.
Group 2 captures companies with consolidated revenue of AUD 200 million or more, consolidated gross assets of AUD 500 million or more, or 250 or more employees. It also captures National Greenhouse and Energy Reporting (NGER) reporters below the Group 1 publication threshold, plus registered schemes and superannuation entities with AUD 5 billion or more in assets, regardless of size. Reporting starts for financial years commencing on or after 1 July 2026.
Group 3 captures companies with consolidated revenue of AUD 50 million or more, consolidated gross assets of AUD 25 million or more, or 100 or more employees. Reporting starts for financial years commencing on or after 1 July 2027. A Group 3 company that concludes it has no material climate-related financial risks or opportunities can lodge a statement explaining that conclusion in place of full climate statements. That statement is itself reviewed by the assurance provider.
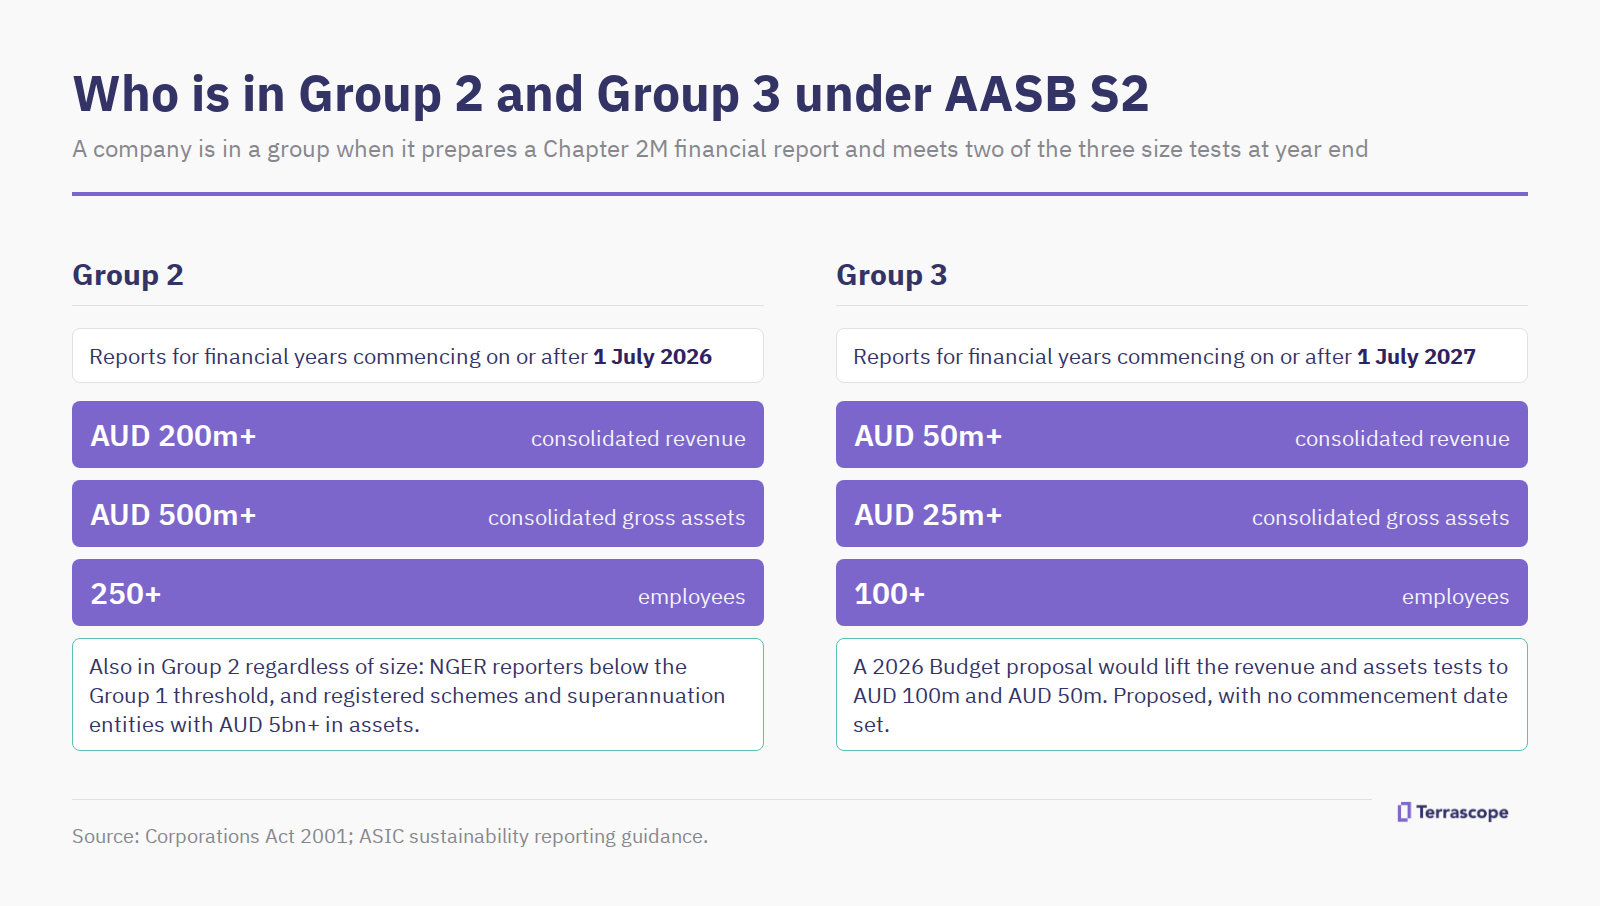
One proposal to watch. The 2026-27 Federal Budget proposed lifting the large proprietary company thresholds to AUD 100 million revenue and AUD 50 million assets, and Treasury consulted on it in a paper that closed on 2 October 2026. If legislated, companies between the current and proposed thresholds would leave Group 3. Treasury has said the changes will affect no entity reporting for the 2026-27 financial year, and has set no commencement date, so a company inside that band should keep preparing until the change is law. The employee test stays at 100.
The date that matters is the first day of your first reporting year
Take a company with a 30 June year end. Group 2's first reporting year runs from 1 July 2026 to 30 June 2027, and the sustainability report is lodged with the 2027 annual report. Group 3's first reporting year runs from 1 July 2027 to 30 June 2028, lodged in 2028.
That first report has to contain climate statements across all four AASB S2 pillars: governance, strategy, risk management, and metrics and targets, including Scope 1 and 2 emissions measured under the GHG Protocol Corporate Standard (NGER reporters can apply NGER methods to the operations that scheme covers). The reliefs in year one are narrow: no comparative figures, Scope 3 deferred to year two, and a lighter scenario analysis requirement. Everything else is due in full, and the directors sign a declaration on it.
Scope 1 and 2 need meter-level and invoice-level data for the whole year, so the collection system has to be live on day one. Scope 3 arrives in year two, and a year-two Scope 3 figure needs a base year, supplier data and a method that the assurance provider will accept, all of which get built during year one.
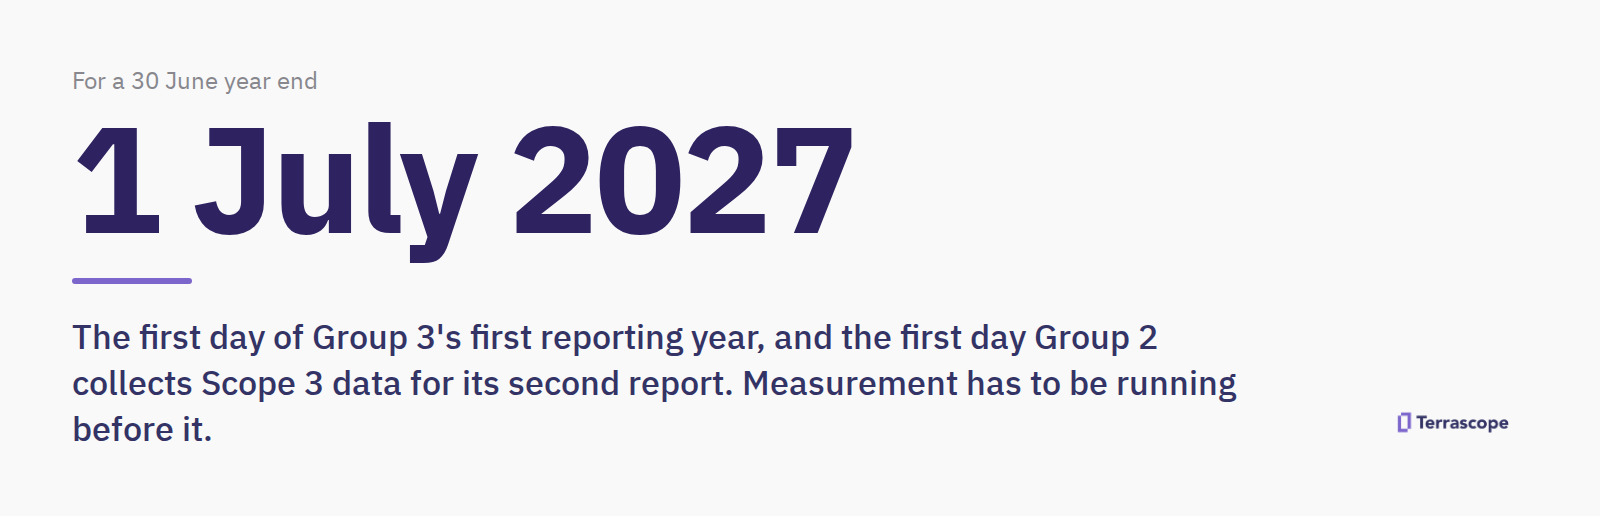
For a company with a June year end, 1 July 2027 is the first day of Group 3's first reporting year and the first day Group 2 companies collect Scope 3 data for their second report. Both groups need their measurement in place before it.
Your customers' Scope 3 request arrives first
AASB S2 requires every reporting company to disclose Scope 3 emissions from its second reporting year. Group 1 companies with calendar financial years entered that year on 1 January 2026. Group 2 companies with June year ends enter it on 1 July 2027. Those companies get the largest share of their Scope 3 figure from purchased goods and services, which means from their suppliers.
Most Group 3 companies supply a Group 1 or Group 2 company. So the first request for your emissions data will come from a customer's procurement or sustainability team, with a deadline set by their reporting cycle, well before your own report is due. Treasury's 2026 consultation on setting boundaries for supplier information requests confirms the pressure is already being felt.
The measurement that answers that customer is the same measurement your own first report needs. Build it once, to the standard your assurance provider will review, and it serves both. Vitasoy proved its emissions were 16% below the industry benchmark and turned that figure into a sales advantage with its customers.
Assurance starts in year one and tightens every year
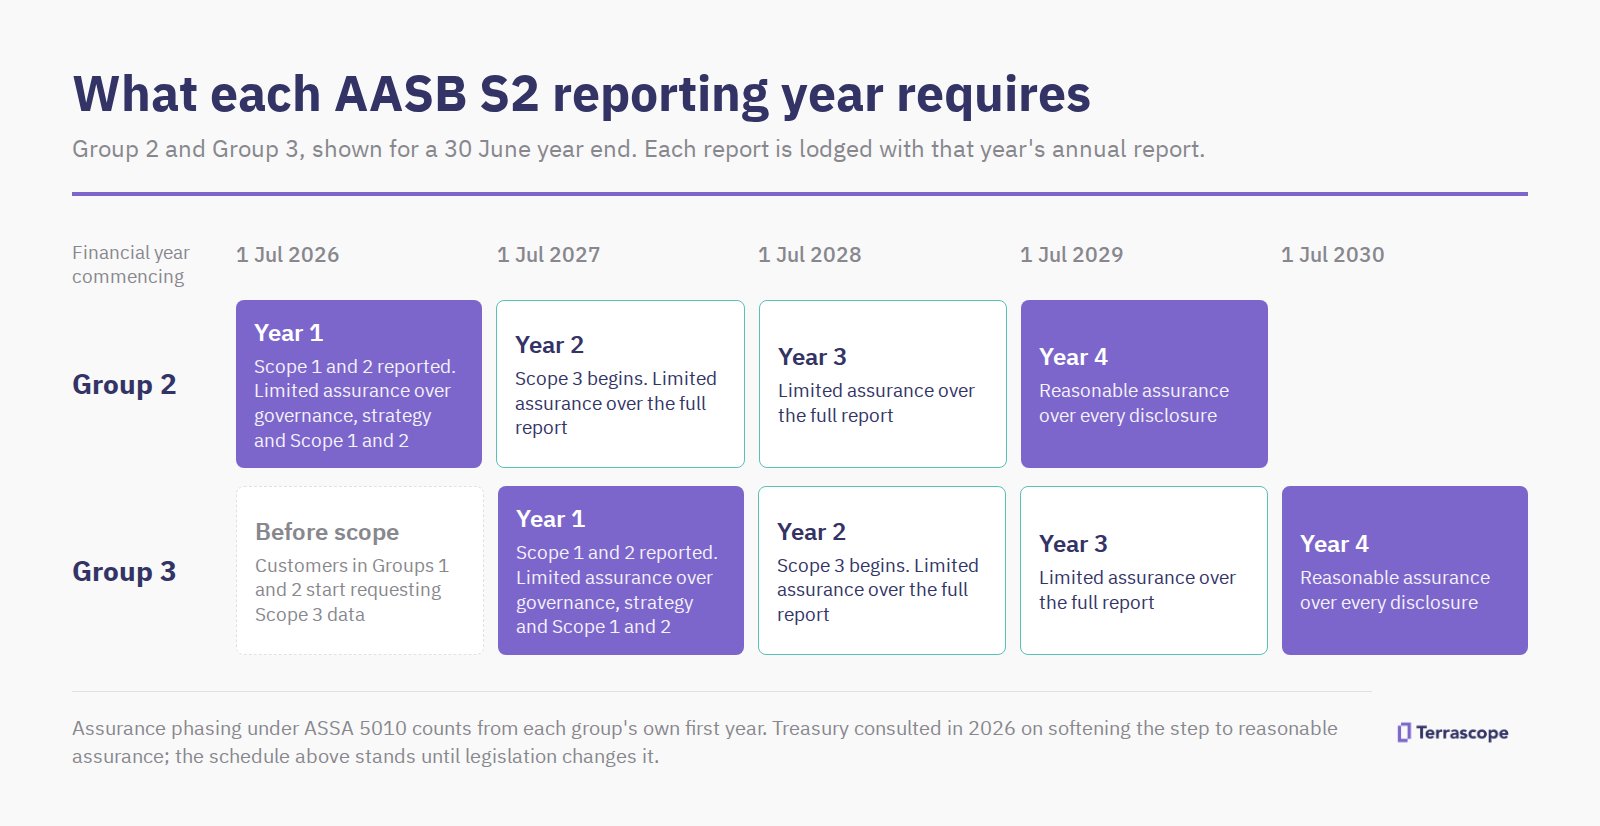
Australia phases assurance in under ASSA 5010, and the phasing counts from each group's own first year:
-
Year one: limited assurance over governance, the strategy disclosures on risks and opportunities, and Scope 1 and 2 emissions.
-
Years two and three: limited assurance over every disclosure in the sustainability report.
-
Year four: reasonable assurance over every disclosure. For Group 2 that is financial years commencing 1 July 2029; for Group 3, 1 July 2030.
Treasury's consultation includes options to soften the step to reasonable assurance, such as keeping limited assurance for Scope 3. Until any of that is legislated, the schedule above stands.
Limited assurance in year one means an auditor will ask for the source of each Scope 1 and 2 figure, the emission factor applied and who approved it. A company that starts collecting data in a spreadsheet and reconstructs the trail at year end spends its first audit explaining gaps.
Dyno Nobel, the Australian-headquartered explosives manufacturer, passed its first global assurance audit a full year ahead of its deadline because the audit trail was built into the measurement from the start.
Different starting points, same first report
If you have never measured, your first job is a Scope 1 and 2 inventory with a documented method, and a Scope 3 screening to find the categories that will matter in year two. If you track emissions in spreadsheets, the job is moving to a system that keeps the evidence trail an assurance provider will ask for. If you already report voluntarily, the job is closing the gap between your current disclosure and the AASB S2 requirements on governance, scenario analysis and targets.
Wherever you start, the first report has the same content, the same review and the same directors' declaration.
How Terrascope can help
Terrascope is a platform with experts built in: software plus climate and carbon specialists who guide you from a first inventory to an audit-ready disclosure.
-
Scope 1, 2 and 3 measurement. Energy, fuel, procurement spend and supplier data flow into a GHG Protocol-aligned inventory, with NGER methods applied where the scheme covers your operations.
-
Audit Trail. Every figure carries its source, emission factor, method and approval history, with reviewer access for your assurance provider matched to the ASSA 5010 phasing.
-
ISSB Reporting. An AASB S2-aligned narrative mapped to each disclosure requirement, produced from the same data set as your CDP and customer submissions.
-
Supply chain intelligence. Category-level Scope 3 hotspots across your supplier base before your second-year deadline, and a supplier data request you can answer when your own customers send one.
The AASB S2 dates will hold. Starting before your first reporting year opens is the difference between a first audit that confirms your numbers and a first audit that finds the gaps.
Speak to an expert
Book a conversation with a Terrascope specialist about your first AASB S2 report.