Summary
Carbon accounting is how a company measures and records the greenhouse gases its activities cause. Emissions are converted to one unit, CO2e, and grouped into Scope 1 (direct), Scope 2 (purchased energy) and Scope 3 (value chain). Most companies follow the GHG Protocol. The result is a footprint you can report, assure and reduce.
What is carbon accounting?
Carbon accounting is the process of measuring, recording and reporting the greenhouse gas (GHG) emissions caused by an organisation. It turns business data, such as fuel bills, electricity use and purchases, into a single number for each source.
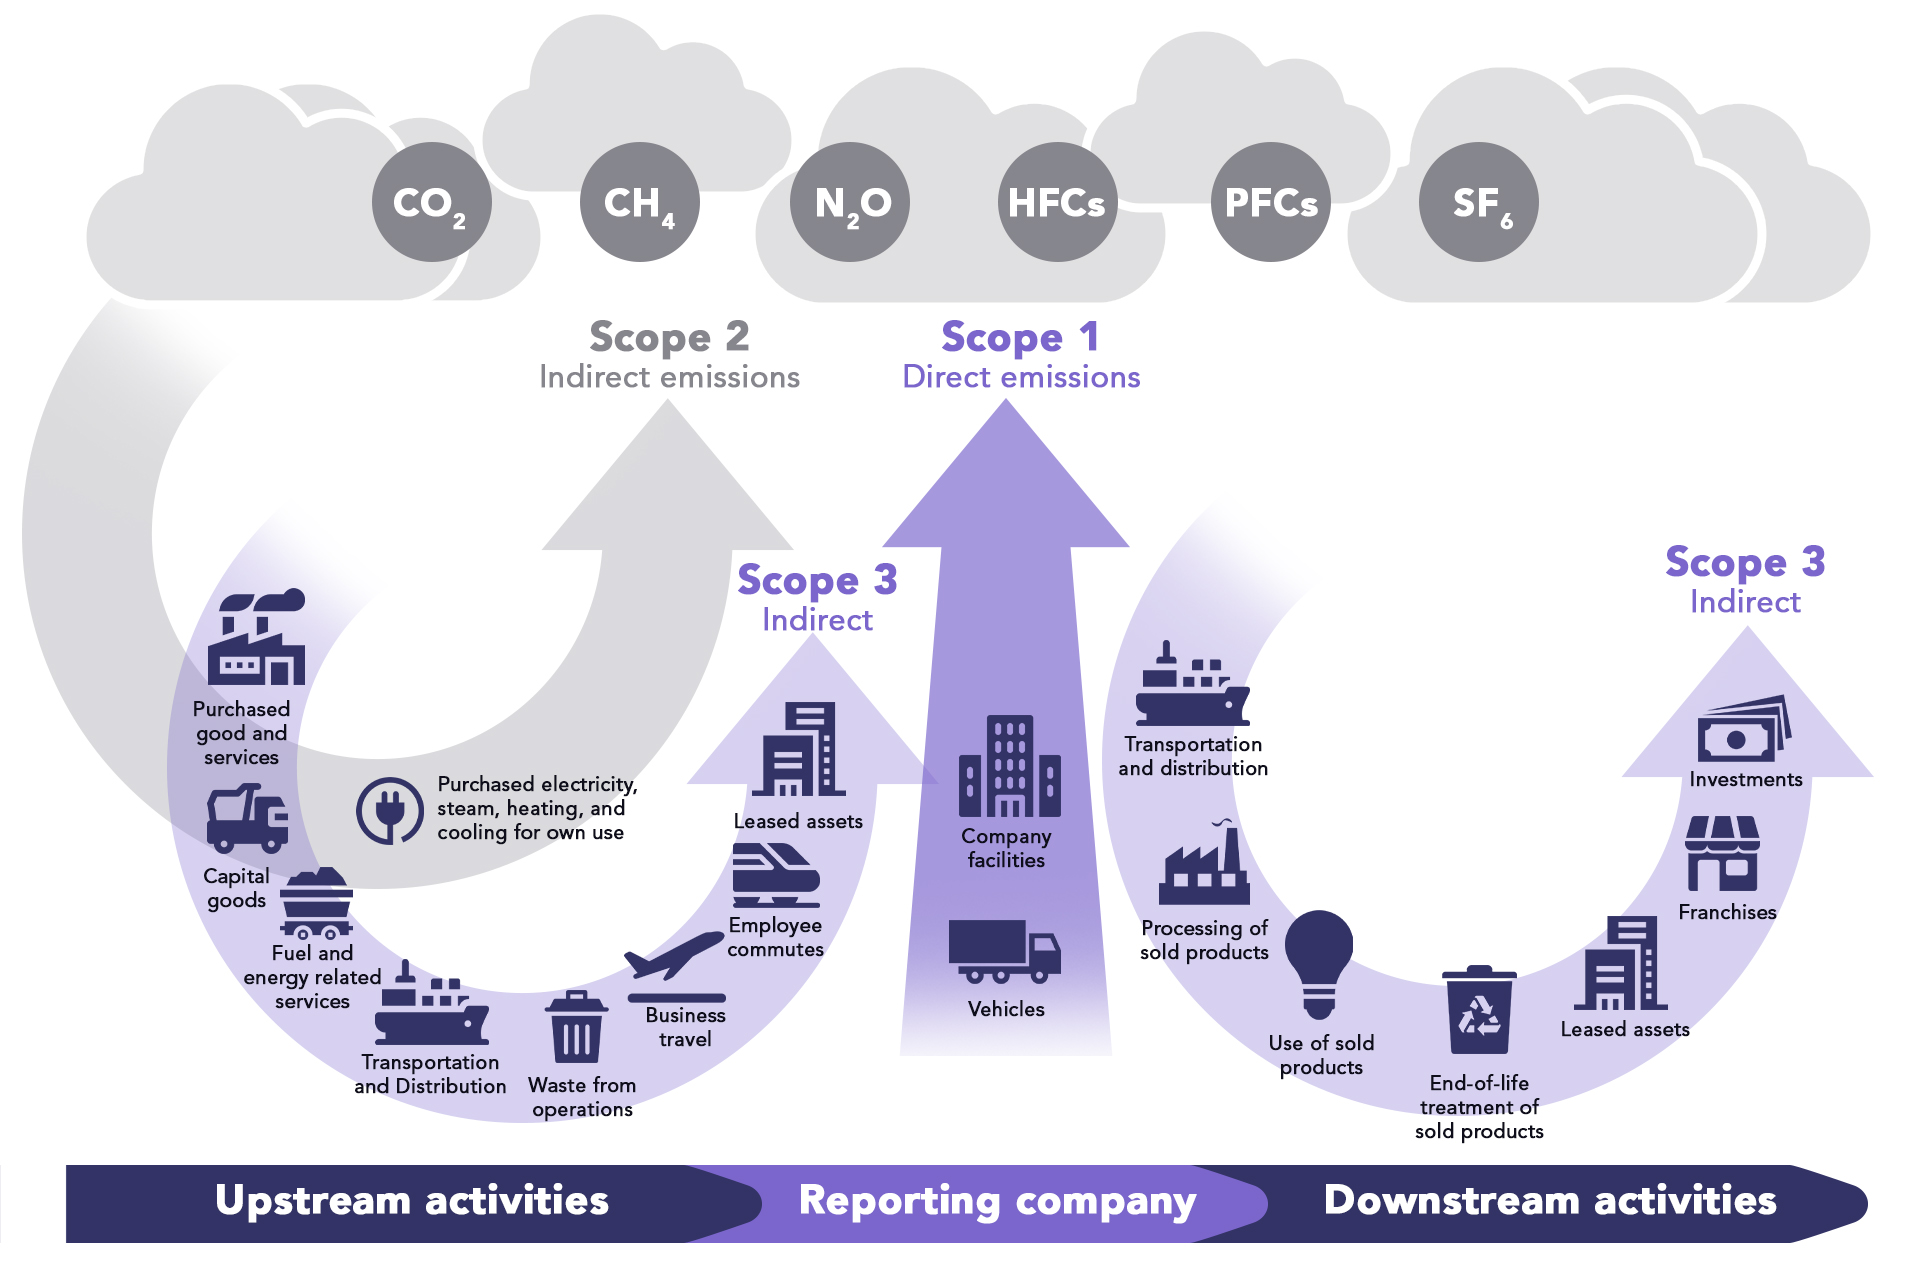
Carbon dioxide (CO2) is the main gas, but the GHG Protocol covers seven: CO2, methane (CH4), nitrous oxide (N2O), hydrofluorocarbons (HFCs), perfluorocarbons (PFCs), sulphur hexafluoride (SF6) and nitrogen trifluoride (NF3). Each gas is converted to CO2e, carbon dioxide equivalent, using its global warming potential. That lets you add them together and compare them.
The output is your corporate carbon footprint: total emissions for a set period, usually a financial year, split by scope.
What are Scope 1, 2 and 3 emissions?
The GHG Protocol Corporate Standard groups emissions into three scopes, based on how close they are to your own operations.
| Scope | What it covers | Typical sources | Typical data |
| Scope 1 | Direct emissions from sources you own or control | Boilers, furnaces, company vehicles, refrigerant leaks, process emissions | Fuel purchase records, meter readings, refrigerant top-ups |
| Scope 2 | Indirect emissions from the electricity, heat, steam or cooling you buy | Grid electricity in offices, plants and warehouses | Energy bills, renewable energy contracts |
| Scope 3 | All other indirect emissions in your value chain, in 15 categories | Purchased goods, transport, business travel, use and disposal of sold products | Spend data, supplier data, product and logistics data |
For most companies, Scope 3 is the largest share. CDP and BCG found that companies disclosing to CDP reported supply chain emissions averaging 26 times their operational (Scope 1 and 2) emissions (CDP and BCG, Scope 3 Upstream: Big Challenges, Simple Remedies, June 2024). Our post on all GHG scope categories explains each scope in more detail, and our Scope 3 emissions guide covers the 15 categories.
How is carbon accounting done, step by step?
Carbon accounting follows five steps: set boundaries, collect data, apply emission factors, calculate and check, then report. The same steps apply whether you use spreadsheets or software.
- Set your boundaries. Decide which entities are in your inventory (organisational boundary) and which emission sources you count (operational boundary). Our guide to GHG inventory boundaries explains the equity share and control approaches.
- Collect activity data. Gather fuel, energy, travel, purchasing and logistics data from finance, procurement, facilities and operations. In large companies this data sits in many systems, which is why data integration in carbon accounting matters.
- Match emission factors. Pair each activity with an emission factor, for example kg CO2e per kWh of grid electricity or per tonne of steel bought.
- Calculate and check. Multiply activity data by the factor, convert to CO2e and add up by scope. Then check for gaps, double counting and outliers. Our step-by-step post on how to calculate GHG emissions includes a worked example.
- Report and assure. Publish totals in the format your audience needs, such as a sustainability report, CDP response or regulatory filing. External assurance is increasingly required for Scope 1 and 2.
Which carbon accounting methods can you use?
You can calculate emissions from spend data, from activity data, or from a mix of both. The right choice depends on the data you have and how precise you need to be.
Spend-based methods multiply what you spent by an average factor per dollar. They are quick but coarse. Activity-based methods use physical quantities, such as kWh, litres or kilograms, and are more accurate. Supplier-specific data is best of all. Most companies use a hybrid: activity or supplier data for their biggest sources, and spend data for the rest. See different methods of carbon accounting for a full comparison, and methods of calculating Scope 3 emissions for value chain specifics.
Which standards and rules apply to carbon accounting?
The GHG Protocol is the base standard for corporate carbon accounting. Most disclosure frameworks and rules either require it or are built on it.
- The ISSB's IFRS S2 climate standard requires companies to measure emissions using the GHG Protocol Corporate Standard (2004), unless a jurisdiction requires another method.
- California's SB 253 requires reporting in line with GHG Protocol standards and guidance.
- CDP questionnaires are aligned with the GHG Protocol, though CDP also accepts some other methods, such as ISO 14064-1.
Our explainer on the GHG Protocol covers what each of its standards does. For country rules and dates, see the end of the sustainability reporting alphabet soup.
What makes carbon accounting hard?
The hard part is data, not maths. Most problems come from getting complete, consistent data from many sources and suppliers.
- Data is scattered. Fuel, energy, spend and logistics data sit in different systems and teams, in different units and formats.
- Supplier data is patchy. Many suppliers do not measure their emissions, and some will not share them. That forces companies to use averages for much of Scope 3.
- Averages hide real differences. Industry-average factors cannot show the gap between a low-carbon and a high-carbon supplier, so they make reductions hard to see.
- Rules keep moving. Frameworks differ on scope, timing and assurance, and the GHG Protocol itself is being revised. Teams need an inventory that can be re-cut for each audience.
Why does carbon accounting matter for a business?
A reliable footprint is the starting point for compliance, targets and reductions. Without one, you cannot set a credible target or show progress.
It helps you meet disclosure rules and customer requests, find your largest emission sources, set science-based targets and track them year on year. Our post on why carbon accounting is important covers the business case in full.
What does carbon accounting look like in practice?
Princes, the UK-based food and drink group, used Terrascope to map its value chain emissions. It found that its top five activities made up more than 60% of its emissions. That told the team where to focus supplier engagement and better data first. Read the Princes case study.
This pattern is common in what we see across customer inventories: a small number of activities drives most of the footprint, so precision there matters more than precision everywhere.
How Terrascope helps with carbon accounting
Terrascope's corporate carbon footprint platform brings Scope 1, 2 and 3 into one auditable inventory.
- Data in one place. Our data management tools take in ERP, spend, energy and supplier data and map it to emission factors.
- Scope 3 by hotspot. Spend-based estimates cover the long tail, while activity and supplier data replace them for the categories that matter most.
- Audit-ready outputs. Every number traces back to its source data and factor, which supports external assurance.
- Reports in the formats you need. The same inventory feeds CDP, IFRS S2 and regional disclosure rules.
If you want to size the effort and savings of moving off spreadsheets, try the carbon accounting ROI calculator.
Ready to build an inventory you can defend? Talk to our team about your carbon accounting needs.
Frequently asked questions
What is carbon accounting in simple terms? Carbon accounting is measuring the greenhouse gases a company causes, converting them to CO2e and adding them up by scope. It works like financial accounting, but the units are tonnes of emissions instead of money.
What is the difference between carbon accounting and a carbon footprint? Carbon accounting is the process. A carbon footprint is the result: the total CO2e for a company, product or activity over a set period.
Do companies have to include Scope 3 in carbon accounting? It depends on the rule. IFRS S2 requires Scope 3 disclosure, with transition relief in the first year. California SB 253 requires Scope 3 reporting from 2027. Even where it is optional, Scope 3 is usually the largest share, so leaving it out gives a misleading picture.
What standard is used for carbon accounting? Most companies use the GHG Protocol Corporate Standard, with its Scope 2 Guidance and Scope 3 Standard. ISO 14064-1 is an alternative used in some markets.
How often should a company do carbon accounting? At least once a year, in line with your financial year. Many large companies now track key sources, such as energy, monthly or quarterly so they can see progress before year end.
Can carbon accounting be done in spreadsheets? For a small company with mostly Scope 1 and 2, yes. For large companies with complex supply chains, spreadsheets become hard to audit, update and scale.