
Summary
Companies decarbonise in six steps. Measure a full Scope 1, 2 and 3 baseline. Set science-based targets. Rank abatement levers by impact and cost. Model decarbonisation pathways. Report progress. Build the plan into budgets and operations. It's a cycle: you remeasure every year and adjust the plan as data improves.
Last updated: 23 October 2026
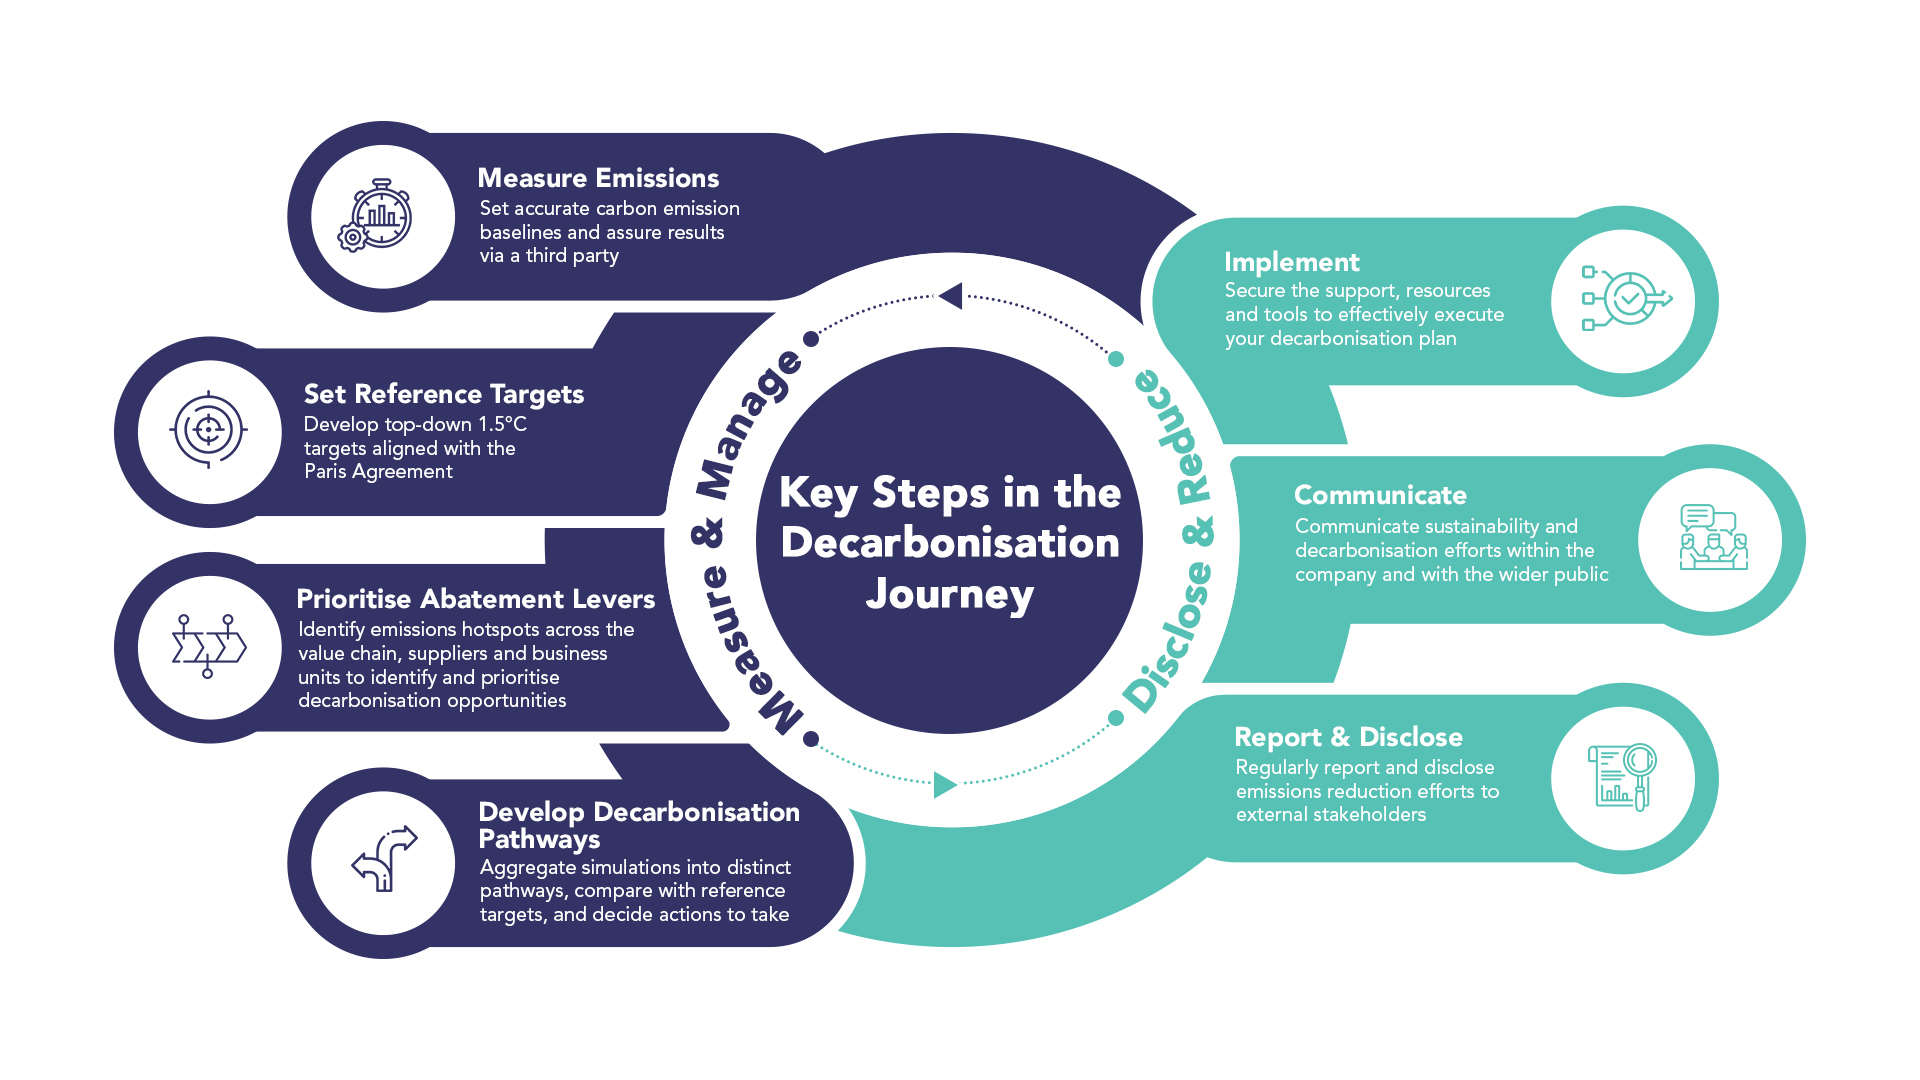
What are the key steps in a company's decarbonisation journey?
The six steps are measure, set targets, prioritise abatement levers, develop pathways, report and implement. Each one builds on the one before.
| Step | What you do | What you end up with | Typical owner |
| 1. Measure emissions | Build a Scope 1, 2 and 3 inventory under the GHG Protocol | An auditable baseline by scope, category, site and supplier | Sustainability, finance |
| 2. Set targets | Set near-term and long-term targets aligned with 1.5°C | Science-based targets, ready for SBTi validation | Sustainability, board |
| 3. Prioritise abatement levers | Rank actions by emissions impact, cost and feasibility | A ranked list of reduction levers | Operations, procurement |
| 4. Develop pathways | Model business-as-usual growth and "what-if" scenarios | Two or three costed pathways compared against targets | Strategy, finance |
| 5. Report and disclose | Report progress to regulators, investors and customers | Disclosures aligned with ISSB/IFRS S2, CDP and local rules | Sustainability, investor relations |
| 6. Implement | Build the plan into budgets, capital allocation, procurement and pay | Funded initiatives with owners and tracking | C-suite, business units |
Step 1: How do you measure your emissions baseline?
Measure all Scope 1, 2 and 3 emissions for a base year, following the GHG Protocol. The baseline is what every target and reduction is measured against.
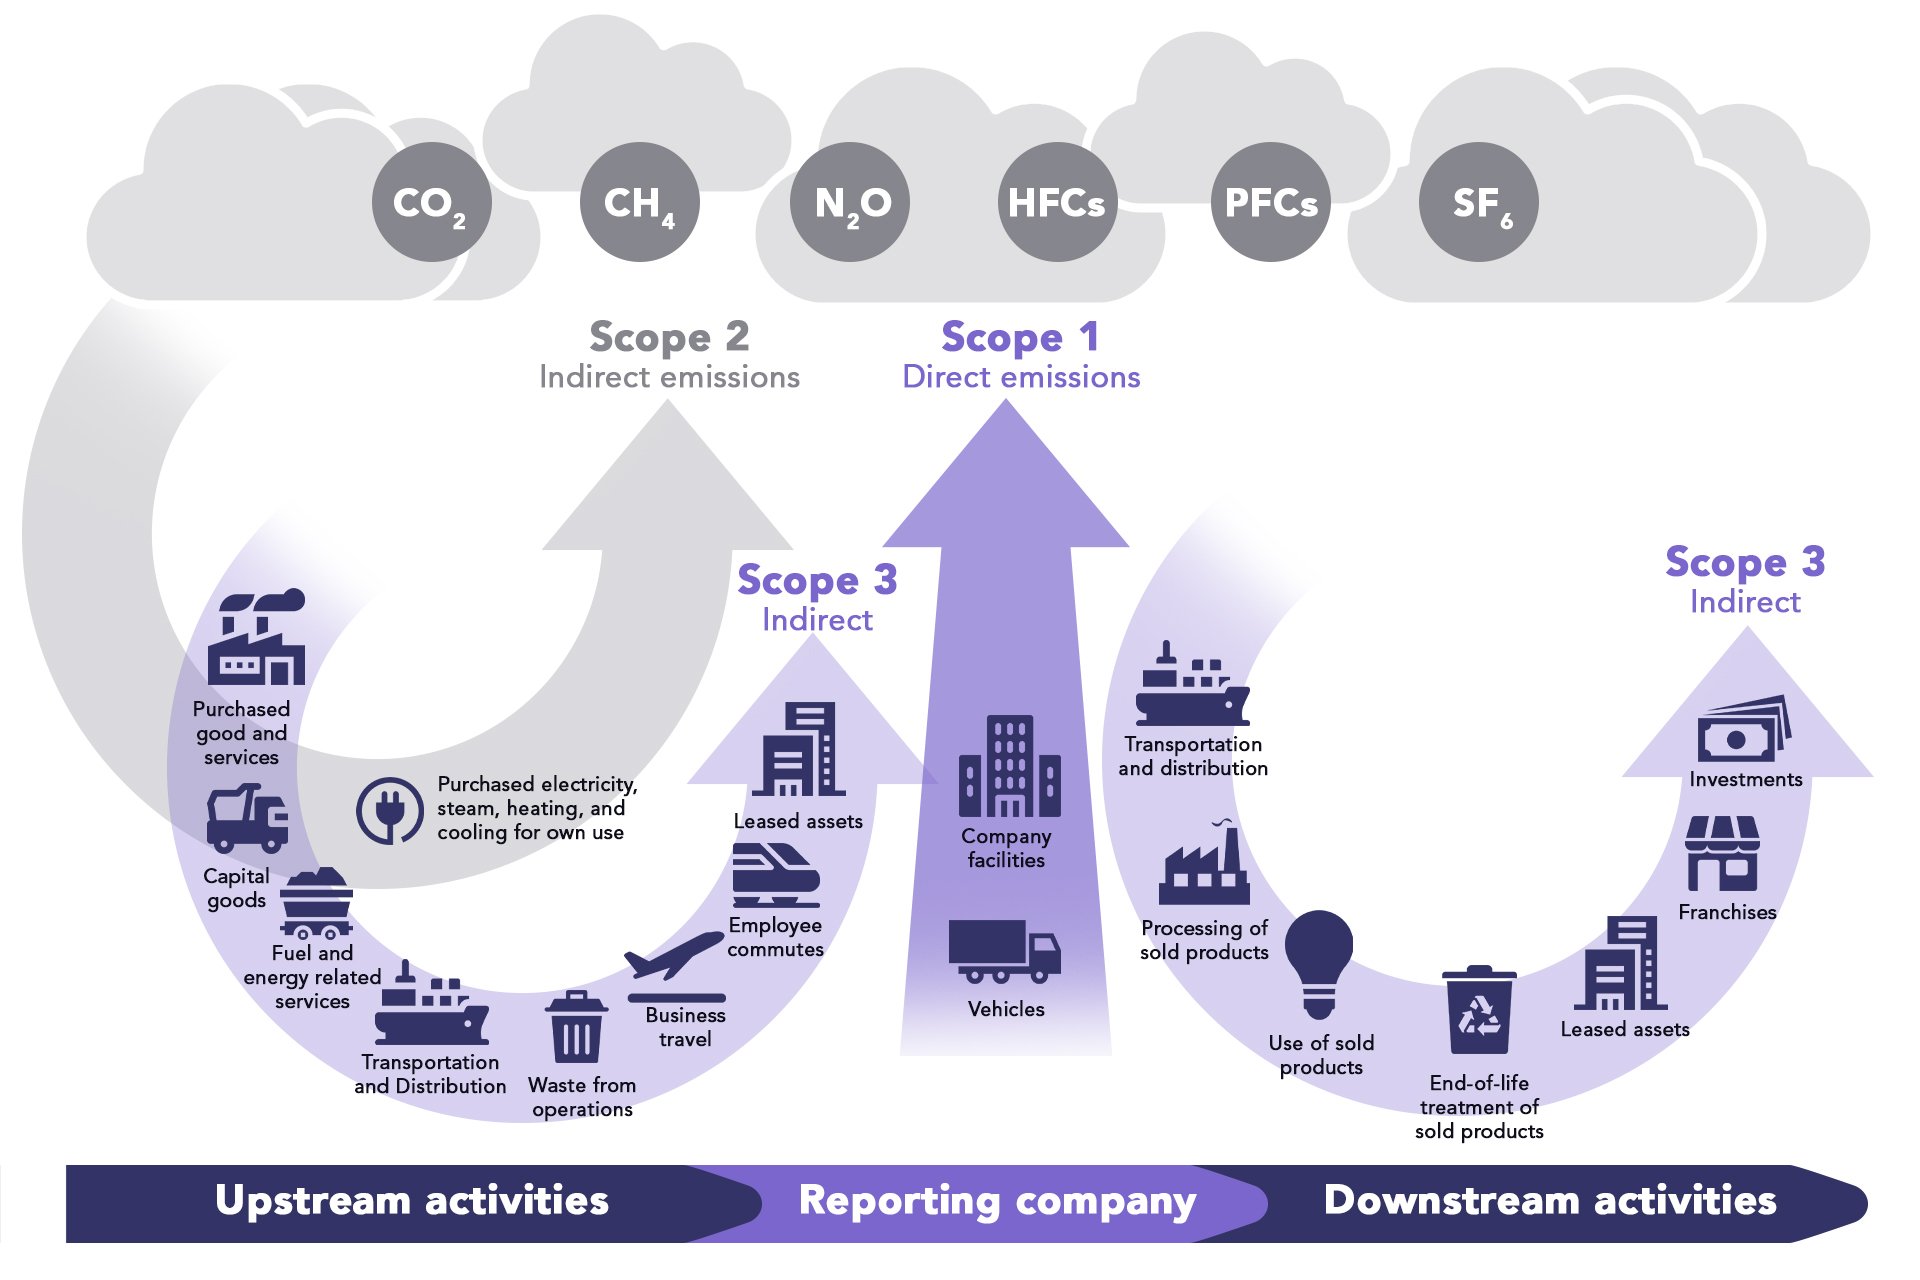
- Scope 1 covers direct emissions from fuel, processes and refrigerants.
- Scope 2 covers purchased electricity, heat and steam.
- Scope 3 covers the other 15 value chain categories, from purchased goods to the use of sold products.
For most companies Scope 3 is the largest share, so it can't be left out. Start with spend-based estimates where you have to, then replace them with activity and supplier data for the biggest categories. Our guides cover how to calculate GHG emissions and Scope 3 emissions.
Step 2: How do you set science-based targets?
Set targets top-down, from what the climate science says is needed, not bottom-up from what feels achievable. The Science Based Targets initiative (SBTi) is the most widely used framework.
- Near-term targets cover roughly the next 5 to 10 years.
- Long-term targets reach net zero by 2050 at the latest.
The SBTi published version 2.0 of its Corporate Net-Zero Standard in June 2026, and companies can use version 1.x until 31 January 2028. See what's changed in SBTi v2.
Investors and ratings agencies also test targets. MSCI, for example, uses an Implied Temperature Rise metric to show how a company's plans line up with Paris goals. A validated target makes those checks easier to pass.
Step 3: How do you prioritise abatement levers?
Rank each lever by how much it cuts, what it costs and how easy it is to deliver. Start with the hotspots in your baseline.
An abatement lever is any action that cuts the activity behind emissions or the emissions per unit of activity. Examples include renewable power, electrified heat, lower-carbon materials, supplier programmes and product redesign.
Use the mitigation hierarchy to order them: avoid first, then reduce, then substitute, and only then neutralise what's left with carbon removals. Credits bought outside your value chain can support wider climate action, but they don't count toward your targets. Our guide to the mitigation hierarchy under SBTi v2 explains each step.
Many of the biggest levers sit with suppliers and customers, so work with them early. See engaging suppliers on Scope 3 reductions.
Step 4: How do you build decarbonisation pathways?
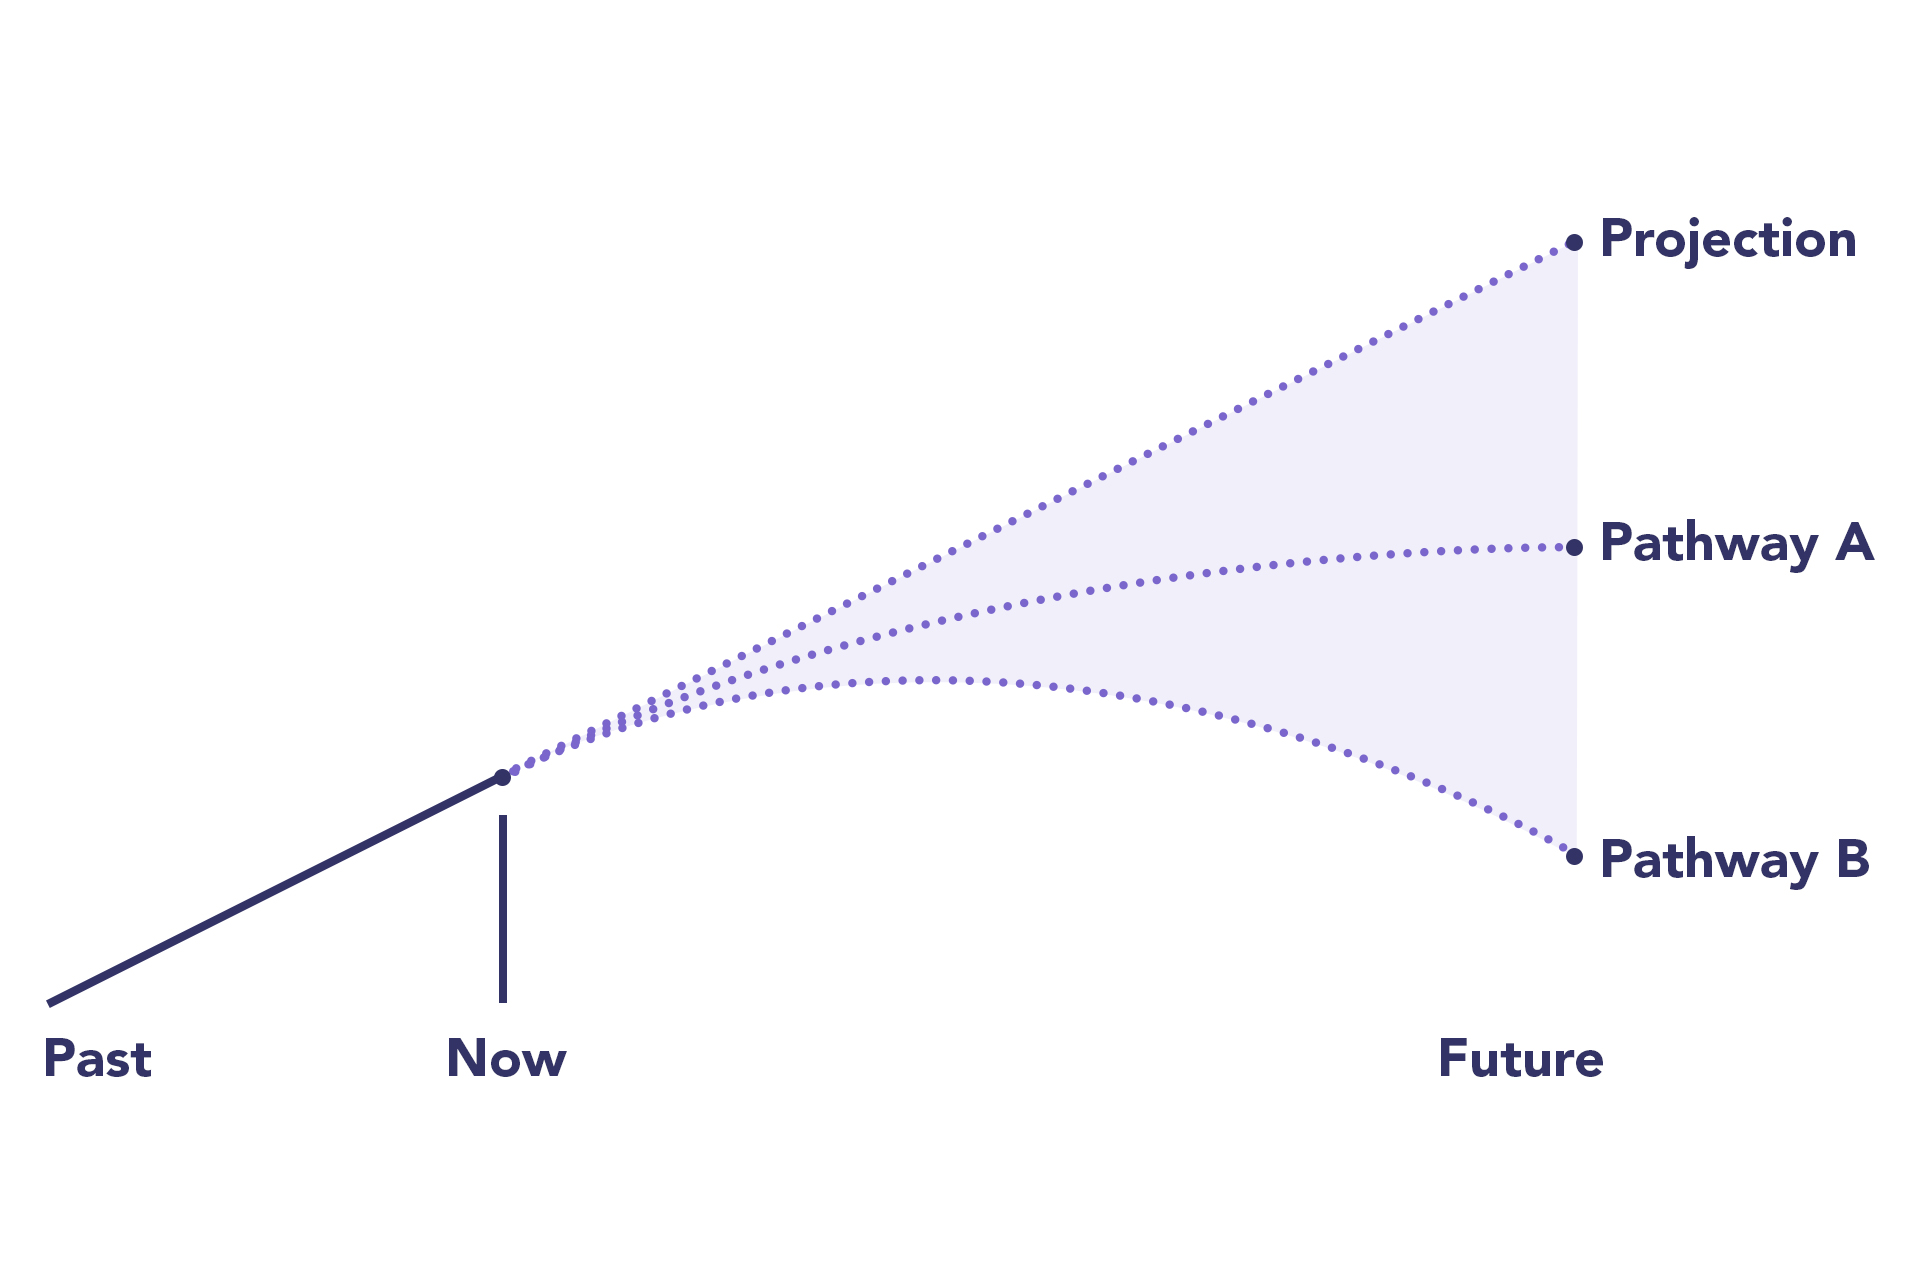
Model how your emissions will change as the business grows, then add your levers in different combinations to see which path reaches the target at the lowest cost.
- Project business-as-usual emissions from your growth plans.
- Run "what-if" scenarios for each lever and timing.
- Group them into two or three distinct pathways.
- Compare each pathway against the targets and its cost.
- Include a carbon price, both current and expected, in the cost. See carbon pricing and CO2e.
Step 5: How should companies report and disclose progress?
Report emissions, targets and progress every year, using the frameworks your regulators and investors expect. More and more large companies are required by law to do this.
- Mandatory disclosure: many jurisdictions now base rules on the ISSB's IFRS S2, for example Australia's AASB S2. Others have their own, such as California's SB 253 and the EU's CSRD. See the sustainability reporting alphabet soup.
- Voluntary disclosure: CDP questionnaires and SBTi progress reporting.
- TCFD: the Task Force on Climate-related Financial Disclosures disbanded in 2023 after its recommendations were built into IFRS S2. Use IFRS S2 or your local standard instead.
Communicate inside the company too. Teams that know the plan and their part in it deliver it faster.
Step 6: How do you implement the plan?
Get C-suite approval and funding, then build the plan into the processes that already run the business.
- Budgets and capital allocation: fund levers through the normal capital cycle, using a carbon price to compare projects.
- Procurement: add emissions criteria to supplier selection and contracts.
- Pay and incentives: link part of executive and business-unit pay to emissions goals.
- Tracking: assign an owner to each initiative and track it against the pathway.
Then go back to step 1. Remeasure every year, improve data quality and update the pathway.
Terrascope customer example: an SBTi-ready baseline
Frutura worked with Terrascope to build an SBTi-ready FY2024 baseline, the starting point for setting science-based targets.
How Terrascope helps
Terrascope supports each step on one platform, with sustainability experts to help you decide.
- Measure (step 1): the Terrascope carbon footprint platform builds an auditable Scope 1, 2 and 3 baseline.
- Prioritise and model (steps 3–4): Decarbonise with AI runs "what-if" scenarios and recommends levers, so you can compare pathways against targets.
- Report (step 5): Terrascope climate reporting prepares data for IFRS S2, AASB S2, SB 253 and other disclosures.
- Land-based companies: the FLAG and LSR solution covers FLAG targets and land emissions.
Ready to set or refresh your targets? Book our science-based targets workshop.
FAQs
What is the first step in decarbonisation?
The first step is to measure a full Scope 1, 2 and 3 emissions baseline under the GHG Protocol. Without it, you can't set credible targets, find hotspots or track progress.
What is a decarbonisation pathway?
A decarbonisation pathway shows how a company's emissions are expected to fall over time if it carries out a chosen set of actions. Companies compare two or three pathways against their targets and costs before choosing one.
What are abatement levers?
Abatement levers are actions that cut emissions, such as switching to renewable power, electrifying heat, using lower-carbon materials or working with suppliers to reduce theirs. Companies rank them by emissions impact, cost and feasibility.
How long does it take to decarbonise a company?
Most large companies plan over 20 to 25 years, with near-term targets for about 2030 to 2035 and net zero by 2050 at the latest. The first baseline and targets come first. Delivery runs through every budget cycle after that.
Is TCFD still relevant?
TCFD disbanded in 2023. Its recommendations live on in the ISSB's IFRS S2 standard, which many countries now use as the basis for mandatory climate disclosure. Companies should report against IFRS S2 or their local equivalent.
Do carbon offsets count toward decarbonisation targets?
No, not under the SBTi. Targets must be met through real reductions. Permanent carbon removals can neutralise a small residual at net zero, and credits can fund climate action beyond your value chain, but neither counts toward reduction targets.